India just had its best market week in nearly six years while US tech sold off. The winning trade was owning what nobody was excited about.
8 min read
THE SUNDAY EDITION
As the world’s technology stocks stumbled, India delivered its strongest market rally in nearly six years. Sometimes the most valuable thing an investment can offer is what it doesn’t own.
There are weeks when the stock market makes you question everything you thought you knew about investing. And then there are weeks when it reminds you of something you knew perfectly well but had somehow managed to forget.
This was one of those weeks.
On Thursday, American technology stocks suffered a spectacular selloff. The Nasdaq plunged 5.5%, wiping roughly $2.5 trillion from its market value in a single session. Investors were suddenly worried about the cost of artificial intelligence, the possibility of tougher regulation, and whether the extraordinary spending behind the AI boom would ever produce an equally extraordinary return.
Across the Pacific, markets in Japan, South Korea, and Taiwan were caught in the same downdraft. The companies supplying the chips, equipment, and infrastructure for the AI revolution were discovering that enthusiasm can disappear considerably faster than a data center can be built.
And then there was India.
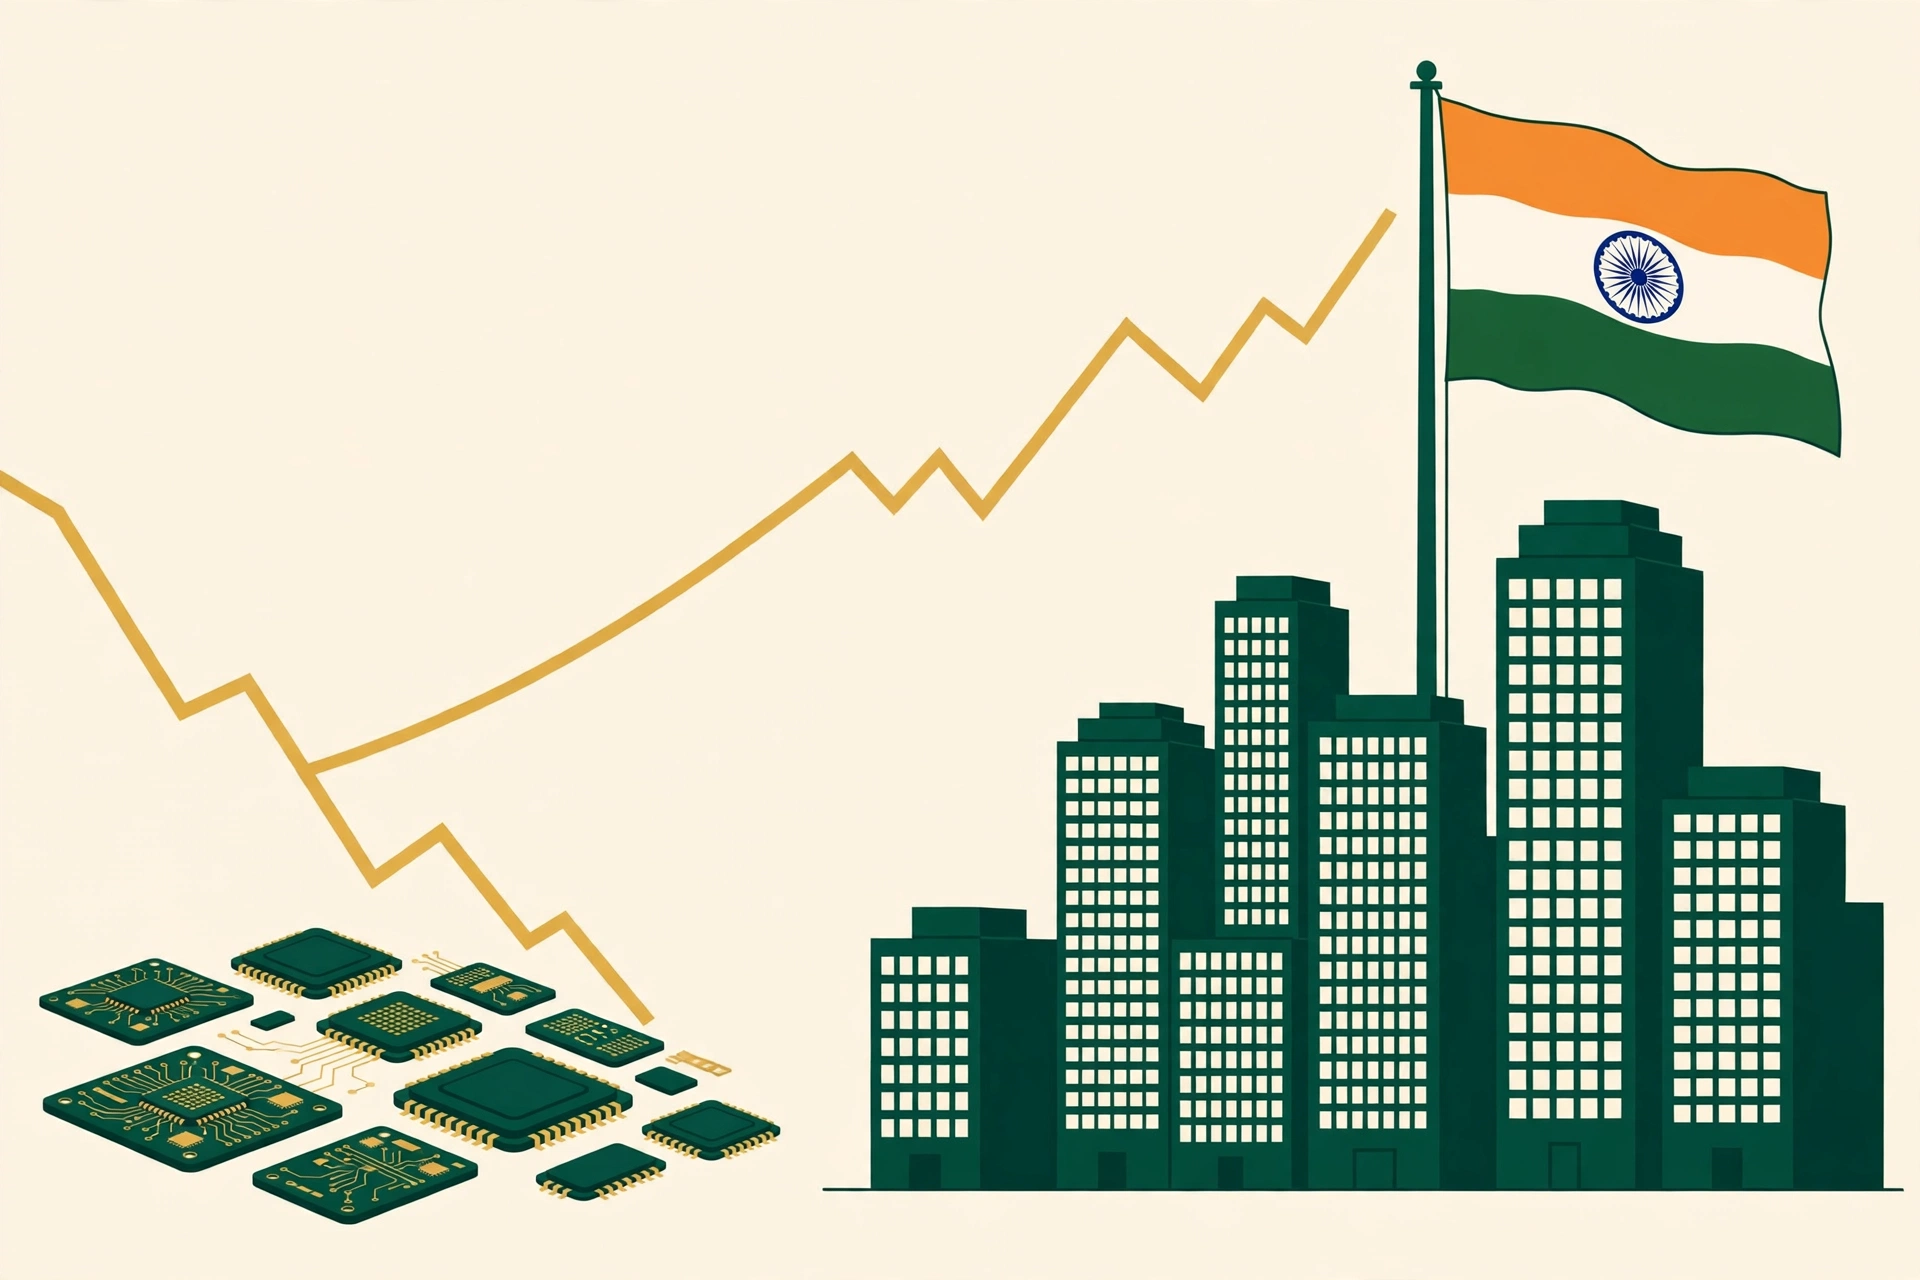
While much of the technology world was having a terrible week, Indian stocks were enjoying their best one in nearly six years.
The country’s benchmark Nifty 50 index climbed 8.6%. The Sensex rose 8.8%. Banks surged, foreign investors returned, and a market that had spent much of the year trailing its emerging-market peers suddenly looked like the place everyone wanted to be.
The curious part wasn’t just that India went up while everyone else went down.
It was why.
For much of the AI boom, India’s relatively limited exposure to the companies building the world’s artificial intelligence infrastructure had been something of a disadvantage. Investors wanted chipmakers, cloud platforms, and businesses promising to power the next industrial revolution. Traditional banks, consumer companies, and businesses tied to domestic economic growth weren’t nearly as exciting.
This week, that disadvantage started looking suspiciously like an advantage.
India hadn’t suddenly invented a better semiconductor. Its companies hadn’t announced a breakthrough that made the rest of the technology industry obsolete.
It simply had less of what investors were suddenly afraid of.
And there’s something wonderfully revealing about that.
Wall Street has a habit of confusing popularity with safety. When an investment performs well for long enough, investors become increasingly comfortable owning it. Rising prices attract attention, attention attracts money, and money pushes prices higher still.
Eventually, what began as a promising opportunity becomes something everyone assumes they need to own.
That’s how a good investment idea can become a crowded investment idea.
The problem with crowded investments isn’t necessarily that they’re bad businesses. Some are extraordinarily good businesses. The problem is that everybody’s expectations start looking remarkably similar.
When those expectations change, there’s a lot of money trying to reconsider its position at roughly the same time.
This week’s market action offered a rather expensive demonstration.
The selloff in American technology stocks followed Tuesday’s U.S. midterm elections, which delivered Democrats control of both houses of Congress. Investors began reassessing the possibility of greater scrutiny over data-center construction, energy consumption, and the broader AI industry.
That political uncertainty landed on a market already questioning the enormous capital commitments required to build AI infrastructure.
It’s one thing to spend hundreds of billions of dollars when investors are celebrating your ambition. It’s another when those same investors begin asking about returns, financing costs, and regulatory obstacles.
None of those concerns appeared overnight. But markets have never needed a completely new problem to justify a sudden change of heart. Sometimes they just need a reason to pay attention to an old one.
India offered an interesting contrast.
The country’s stock market is heavily influenced by banks, financial services, energy, consumer businesses, and other companies whose fortunes aren’t directly dependent on the next generation of AI chips.
That doesn’t make Indian companies immune to technological disruption or global economic weakness. It does mean the market’s immediate risks look different.
And different was suddenly attractive.
Indian financial stocks gained 10.4% during the week. HDFC Bank and ICICI Bank, two of the country’s largest private lenders, rose 13.8% and 12.4%, respectively. Reliance Industries, the sprawling conglomerate with interests ranging from energy to retail and telecommunications, gained 13.3% following encouraging quarterly results.
These aren’t obscure speculative companies. They’re businesses deeply connected to India’s domestic economy.
There was another important ingredient: oil.
India imports most of the crude oil it consumes, making energy prices a significant influence on its economy. Lower crude prices can ease pressure on inflation, reduce import costs, and improve the financial outlook for businesses and households.
Oil prices fell during the week, adding another reason for investors to reconsider Indian assets.
Politics played a role here, too. Some investors interpreted the U.S. election results as potentially limiting further trade and geopolitical disruptions, a development that could benefit an economy sensitive to global energy prices and international capital flows.
So this wasn’t simply a case of investors abandoning artificial intelligence and discovering India. It was a combination of changing expectations, falling oil prices, renewed foreign investment, and a market whose composition suddenly looked appealing.
On Thursday alone, foreign institutional investors bought approximately $1.6 billion worth of Indian shares, their largest single-day net purchase in nearly six years.
Money moves quickly when the narrative changes.
But the more interesting lesson is what happened before this week’s rally.
Through much of 2026, Indian stocks had been disappointing investors. Even after their remarkable recovery, the Nifty and Sensex remained down 4.2% and 4.9% for the year, while the broader MSCI Emerging Markets index was up about 7%.
In other words, India’s spectacular week didn’t erase a difficult year.
That’s worth remembering because financial markets have a remarkable ability to make whatever happened most recently feel inevitable.
When AI stocks were climbing, their dominance seemed entirely logical. When Indian stocks were lagging, investors had plenty of explanations for why they weren’t attractive.
Then the market changed its mind.
The underlying businesses didn’t transform overnight. What changed was how investors valued the risks and opportunities they already knew existed.
It’s one of the peculiar features of investing. A company can become more attractive without improving its business at all, simply because its price falls or the alternatives become less appealing.
The reverse is equally true. An excellent company can become a poor investment if the price assumes everything will go perfectly.
That distinction tends to disappear during a bull market. It’s much easier to discuss the future of artificial intelligence than to explain why a perfectly ordinary bank might deserve a place in a portfolio.
Banks rarely inspire the same excitement as machines that can write software, analyze medical images, or generate convincing videos of things that never happened.
They mostly lend money, collect interest, manage deposits, and occasionally remind customers about overdraft fees.
Hardly the stuff of science fiction.
Yet there they were this week, helping lead one of the world’s strongest market rallies.
There’s a broader point here about diversification, a concept that receives plenty of praise in theory and considerably less enthusiasm when one particular investment category seems to be making everyone rich.
Diversification can feel disappointing when the market’s hottest stocks keep climbing. The assets that provide balance often look boring, unnecessary, or simply inferior.
Until the market changes direction.
Then boring becomes resilient. Overlooked becomes undervalued. And the investment everyone was questioning suddenly becomes the one everyone wishes they’d owned.
Of course, one exceptional week doesn’t establish a new investment trend. India’s economy still faces challenges, its market remains vulnerable to global capital flows, and its stocks are not automatically cheap simply because they’ve underperformed.
Nor does the technology selloff mean AI is finished. The industry’s long-term potential remains substantial, even if investors are becoming more selective about the price they’re willing to pay for it.
But the contrast between India and the technology-heavy markets offers something worth thinking about over Sunday coffee.
Investors spend an enormous amount of time trying to identify the next great opportunity. They study earnings forecasts, follow industry trends, and search for companies positioned to benefit from whatever technology or economic transformation is capturing the world’s attention.
All perfectly reasonable activities.
What receives less attention is the risk of everybody reaching the same conclusion.
When the entire market falls in love with one story, even a good story can become dangerous. Not because the underlying idea is wrong, but because the price of believing it has become so high.
India’s rally wasn’t proof that investors should abandon technology or rush into emerging markets. It was a reminder that financial opportunity doesn’t always arrive with an exciting new invention or a compelling presentation about the future.
Sometimes it comes from a perfectly ordinary collection of businesses that investors have spent months ignoring.
And sometimes, the best thing an investment can have going for it is that nobody has been talking about it.
— Greg Ranieri, Editor-in-Chief
KEEP READING
Sources: Reuters reporting, November 4–7, 2026.
New posts by email
One short email when a new Financial Spark story publishes. No newsletter, no spam — unsubscribe anytime.